
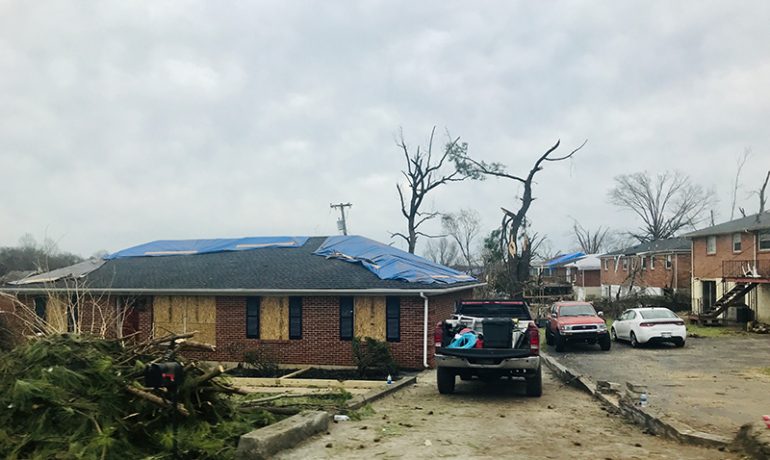
Property insurance typically includes storm damage, but homeowners and businesses should ensure they have the right types and levels of cover in their policies.
Here are some of the issues to consider.
Property cover
Make sure you have adequate property insurance cover for the current cost of re-building and replacing contents in case of disasters. This helps reduce the risk of out-of-pocket costs in the event of damage or losses due to severe storm or other disasters.
Policy inclusions / exclusions
Storm cover can differ between insurers, so you should check your Policy Disclosure Statement for details on what is and isn’t covered.
Depending on where you live and your risk level, this includes checking your policy for the following events:
- Storms, hail, and cyclones
- Landslides (due to storms)
- Strong winds
- Fallen trees
- Rainwater runoff
- Water entry into your home through an opening
- Storm surge caused by wind and ocean movement
- Damage to / loss of outdoor furniture
- Floods – this is often excluded from property insurance and may require a separate policy.
Business interruption
Business owners should consider interruption cover in case of being out of action following a disaster. This insurance typically covers income loss, ongoing expenses and alternative premises rental during repairs or re-building.
Lowering the risk of claim denials
You can lower the possibility of having a storm damage claim rejected by looking after your roof, clearing gutters and trimming trees. People in high-risk areas may also wish to consider storm shutters and more frequent roof upgrades.
Ask your nearest Reliance Partner for advice on ensuring your assets are appropriately protected.